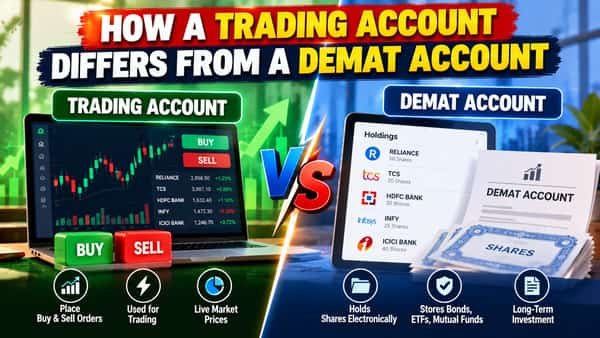
Unused demat account holdings stay safely yours: the shares remain recorded in your name with the depository, they continue to receive dividends, bonus shares, and splits, and nothing is sold or confiscated just because you haven’t traded. What changes is the account’s status, since after a period of inactivity (generally 12 months under SEBI’s framework) it can be classed as dormant, which means you’ll need to reactivate it before you can sell or transfer. Over a longer stretch, unpaid maintenance charges, outdated contact details, lapsed KYC, and unclaimed dividends can create real complications, including the transfer of shares to a government investor fund after seven years. Knowing exactly what happens at each stage makes it easy to keep forgotten holdings safe. This is general information, not investment or tax advice.
The Short Answer
- Your holdings don’t disappear. Securities in a demat account are held electronically with a depository (CDSL or NSDL) in your name.
- Corporate benefits keep coming. Dividends go to your linked bank account, and bonus shares, splits, and rights entitlements are credited to the account, even without any trading activity.
- The account may become “dormant.” After a continuous period with no transactions, typically 12 months under SEBI’s framework, it can be marked inactive or dormant.
- Dormant isn’t closed. A dormant account can be reactivated, whereas a closed account cannot be used again.
- Charges can continue. Annual maintenance charges may keep accruing, depending on your provider.
- Long-term neglect carries risks, including KYC freezes and transfer of shares to the Investor Education and Protection Fund (IEPF).
Stage One: Months of Inactivity
In the first year or so of not using the account, little changes.
- You can still view and monitor holdings through your broker’s app or the depository’s statements.
- Corporate actions are processed automatically, so a stock split or bonus issue will appear in your holdings.
- Dividends are paid to your bank account as long as the bank details on record are valid.
- Annual maintenance charges may apply, depending on your plan. Some providers charge a one-time or lifetime fee instead.
Stage Two: The Account Becomes Dormant
SEBI’s March 2024 framework defines an inactive or dormant demat account as one with no transaction for 12 months continuously. Providers may apply their own policies within the rules, and some allow longer periods before classifying an account as dormant, depending on your agreement and fee structure.
What dormant means in practice:
- You generally can’t sell or transfer shares until the account is reactivated.
- Credits still arrive, such as dividends, bonus shares, and rights entitlements.
- Verification may be required before reactivation, such as re-KYC and signature or identity checks.
- Your securities are unaffected. The dormant label is about transaction activity, not the safety of the holdings.
A June 2026 report citing December 2025 data said that roughly 21.6 crore demat accounts existed in India but only about 5 crore saw activity in the preceding year, so dormancy is very common and doesn’t signal anything unusual about your account.
Stage Three: Charges Add Up
- Annual maintenance charges (AMC) may continue to accumulate on a dormant account, depending on the provider.
- Unpaid dues can pile up. As a simple illustration, an unpaid charge of ₹300 a year would reach ₹1,500 over five years, plus any applicable taxes or penalties.
- Some providers restrict the account until dues are paid, and you may need to clear accumulated charges when reactivating.
- Fees vary. Of the possible charges, policies on maintenance and reactivation differ by provider, so check your agreement.
Stage Four: KYC and Contact Details Go Out of Date
- Changed mobile numbers or emails mean you may miss alerts about corporate actions, statements, and verification requests.
- Lapsed or incomplete KYC can lead to restrictions, which may affect your ability to receive some benefits or complete transactions.
- Closed or changed bank accounts can cause dividends to fail, leaving them returned to the company as unclaimed.
- Outdated signatures or addresses can slow down reactivation.
Stage Five: Unclaimed Dividends and the IEPF
This is the most important long-term risk.
- If dividends on shares remain unclaimed for seven consecutive years, the company is required to transfer both the unclaimed dividend and the underlying shares to the Investor Education and Protection Fund (IEPF).
- The shares move out of your demat account into an IEPF account held by the authority.
- You can still reclaim them, but the process takes effort. You file Form IEPF-5 on the IEPF portal, along with supporting documents such as proof of identity and bank details, and the authority verifies and processes your claim.
- Prevention is easier than recovery. Keeping your bank details current, claiming dividends regularly, and checking your holdings help avoid the transfer.
The Nomination Risk
- Without a valid nominee, your family may find it hard to claim the holdings if something happens to you, and transmission can require more documents, time, and legal formalities.
- A forgotten account with no nominee and no records can become an unclaimed asset that heirs don’t even know exists.
- Adding or confirming a nominee is a quick step that can save significant trouble later.
Security Risks of Neglected Accounts
- Fraud can go unnoticed. Unmonitored accounts with active login credentials and outdated contact details are easier for bad actors to target.
- Unused permissions can linger, such as standing authorisations for a broker to debit your shares.
- Old credentials may be reused elsewhere, increasing exposure.
Checking in regularly and removing permissions you no longer need reduces this risk.
How to Reactivate a Dormant Account
Steps vary by provider, but typically:
- Contact your DP or broker and ask for the reactivation process, or follow the instructions in the email or notice they sent.
- Submit the request, often through the app, website, or a short form.
- Complete verification, such as re-KYC, identity confirmation, and signature checks.
- Pay pending dues, if any, including accumulated annual charges.
- Wait for confirmation, which often takes a few working days.
Some providers charge a reactivation fee, and others waive it, particularly when the account holds securities.
What Your Options Are
- Keep the account and use it occasionally, which can prevent dormancy, though many long-term holders simply hold.
- Reactivate and consolidate your holdings into one account with lower fees.
- Transfer holdings to another account and close the unused one.
- Sell holdings you no longer want, after considering taxes.
- Switch to a lower-cost plan or a basic services demat account if you qualify.
- Close the account properly after transferring or selling everything, as covered separately.
A Simple Maintenance Routine
- Check your holdings at least twice a year, through statements or the app.
- Keep contact details current: mobile number, email, and address.
- Keep your bank account details valid so dividends arrive.
- Confirm your nominee and update it after life changes.
- Complete or refresh KYC when asked.
- Know your charges, and pay or renegotiate them.
- Claim dividends and corporate benefits as they arise.
- Keep records of purchases and statements for tax and heirs.
- Share account details with a trusted family member, such as where the account is held and how to find it, without sharing passwords.
- Search the IEPF portal if you suspect old holdings or dividends went unclaimed.
Frequently Asked Questions
Q1. Will my shares be sold if my demat account is dormant?
A. No, your holdings remain yours, and a dormant status only restricts transactions until you reactivate the account.
Q2. Do I still get dividends in a dormant account?
A. Yes, dividends and bonus shares are credited as usual, provided your bank details and account records are valid.
Q3. When does a demat account become dormant?
A. Under SEBI’s framework, an account is considered inactive or dormant after 12 months of continuous inactivity, though providers’ policies can vary within the rules.
Q4. What happens if I don’t claim dividends for years?
A. After seven consecutive years of unclaimed dividends, the company must transfer the dividends and the shares to the IEPF, from which you can claim them back through Form IEPF-5.
Q5. Do I have to pay charges on an unused demat account?
A. It depends on your provider and plan, since many charge an annual maintenance fee even without trading, so check your agreement and clear any dues.